
 My Agento
Car Repair and KASKO Claims After an Accident
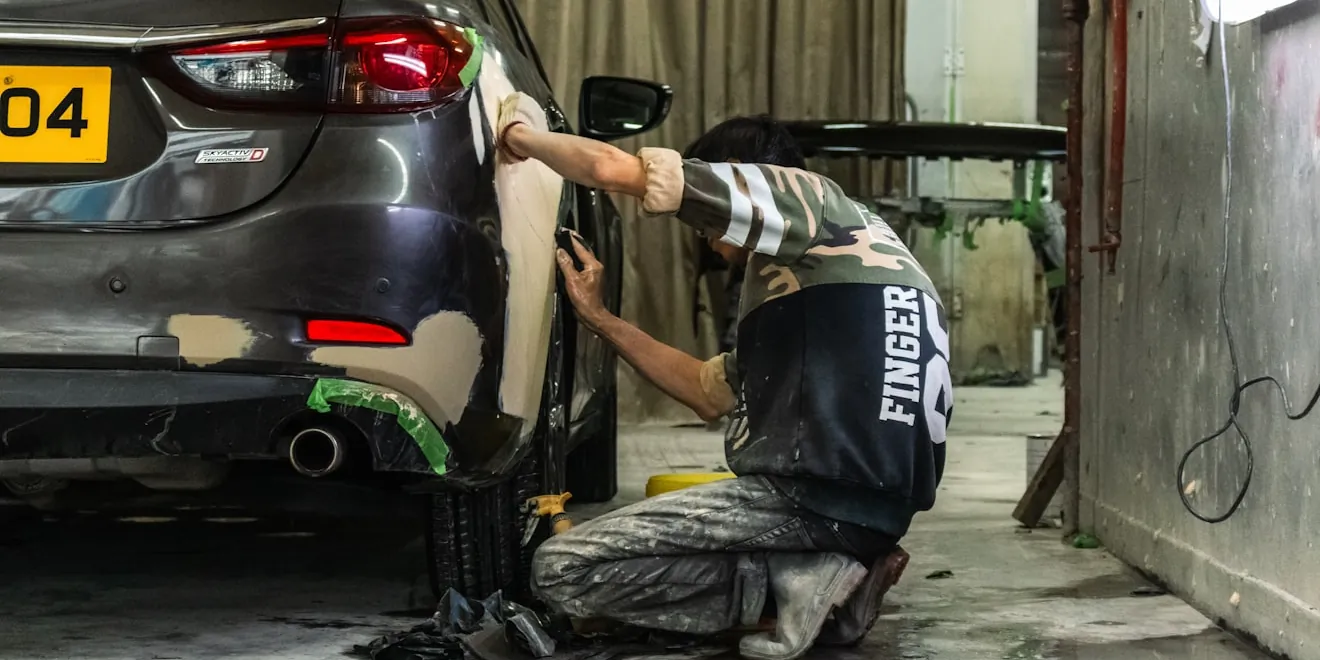
A damaged car after an accident is a situation where you want clarity as soon as possible. How long will it take, where will the car be repaired and how much will you have to pay yourself are questions that come up within the first few minutes. The answers depend largely on the policy you hold and how the first steps are handled.
The KASKO claims process isn't complicated once you understand its logic. The insurer assesses what happened, determines the extent of the loss and then either arranges the repair or pays compensation in cash. Below we explain how this works in practice, which choices are yours to make and what you can do to keep things moving.
How the KASKO claims process works
Everything starts at the scene. The more accurately the event is recorded, the fewer questions arise later. If two vehicles are involved and nobody is injured, you usually fill in an accident report, a standardised form for recording the circumstances. It's also worth taking photographs from several angles, covering the condition of both cars and the surrounding situation.
After that, the event has to be reported to the insurer. Reporting can usually be done electronically, and the sooner it happens, the sooner the assessment begins. The report should describe the circumstances and include photographs and documents confirming what took place.
Once the report is received, the insurer arranges an inspection of the damage. The car is assessed to determine the extent of the damage and the cost of repair. At this stage hidden damage that isn't visible from the outside may also come to light, so the final figure sometimes differs from the initial estimate.
The typical sequence looks like this:
- recording the event and completing documents at the scene
- submitting the claim to the insurer
- inspection and assessment of the damage
- decision on the form and amount of compensation
- repair at a workshop or payment in cash
More about filing claims and the steps involved can be found in the claims section, which brings together practical information about different insurers.
Repair at a workshop or compensation in cash
One of the most common questions is who chooses the repair shop. The answer is in the policy. Some KASKO policies provide for repair at a workshop partnered with the insurer, others let you choose the workshop yourself, and there are also options where newer cars are repaired at an authorised dealership. This condition affects both the price of the policy and your freedom after an accident, so it's worth clarifying when buying the policy rather than when the car is already damaged.
The second question is the form of compensation. The insurer can pay the workshop directly for the repair or pay you in cash. A cash payment is usually calculated from the repair estimate, with the deductible set in the policy subtracted from it. If you choose cash and repair the car more cheaply or postpone the repair, the difference stays with you, but bear in mind that unrepaired damage can affect taking out a policy in future.
The deductible is the amount the vehicle owner covers themselves. It's subtracted from the compensation, so in the case of minor damage it's sometimes more sensible to repair the car at your own expense without filing a claim. It's worth doing this calculation before submitting a claim, comparing the repair cost with the deductible.
When choosing between repair and cash, it's worth considering:
- whether the workshop gives a guarantee on the work done
- whether original or equivalent parts are used
- how long the car will be unavailable and whether the policy includes a replacement vehicle
- how the choice will affect the value of the car if you plan to sell it
If another driver is at fault, the situation is different. In that case the losses can be compensated by the OCTA of the party at fault, and using your own KASKO isn't compulsory. In practice many people choose KASKO for speed, but it's worth exploring both options. You can calculate and compare OCTA offers using the OCTA calculator.
The process moves faster when the paperwork is in order from the start. Clear photographs, an accurately completed report and a prompt claim prevent most follow-up questions. If the damage is serious and the car cannot be driven, it's worth finding out straight away whether the policy includes towing.
Claim conditions differ from policy to policy, and it's the details that decide how smooth the process will be in a real situation. An insurance broker can explain the terms of different policies regarding workshop choice, deductible and form of compensation, and help you pick a solution that suits your car and budget. Get in touch for a consultation today and know exactly how you will act if something happens.